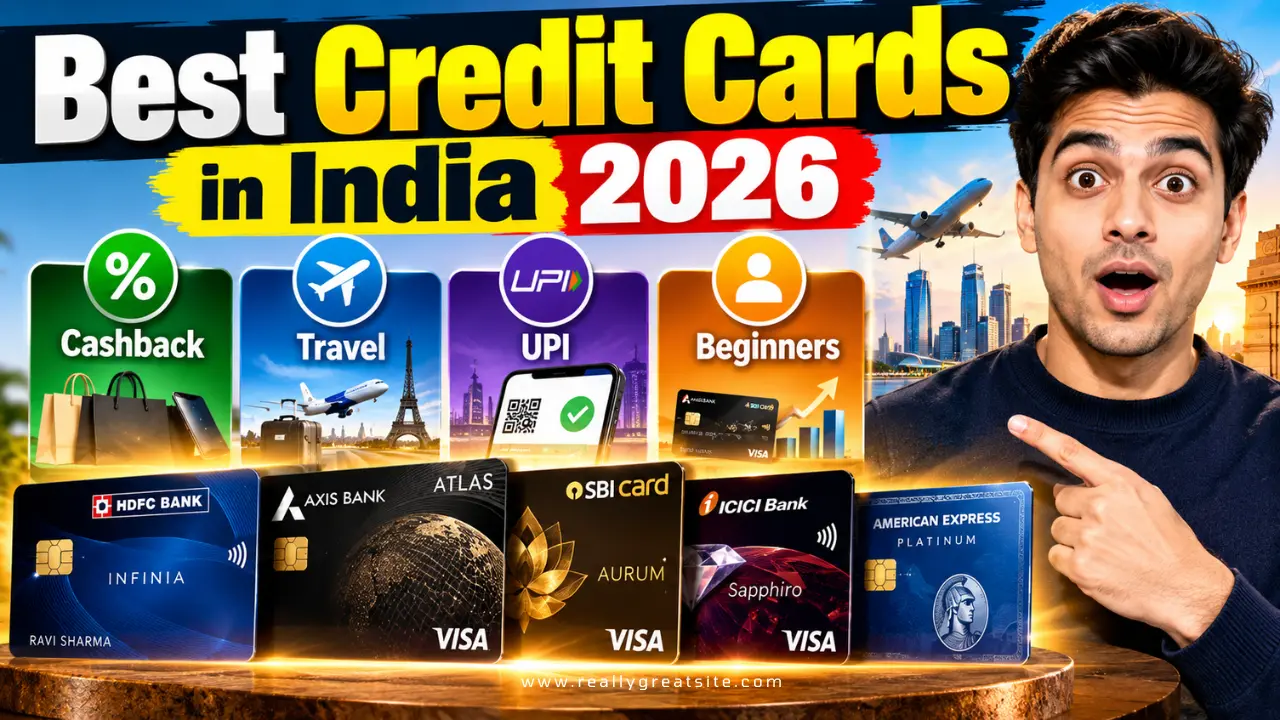
Choosing the right credit card in India can be confusing. There are hundreds of cards available, and every bank highlights different benefits such as cashback, reward points, airport lounge access, travel benefits and discounts.
But the best credit card is not necessarily the one with the highest cashback or the most premium benefits. It depends on how you spend your money.
For example, someone who shops regularly on Amazon may benefit from an Amazon-focused card, while someone who spends heavily online may prefer a cashback card. Frequent travellers may be better served by a travel rewards card.
In this guide, we look at some of the best credit cards in India in 2026 and explain who they may be suitable for.
Best Credit Cards in India 2026
Here are some popular credit cards worth considering based on different spending needs:
| Credit Card | Best For | Key Benefit |
|---|---|---|
| SBI Cashback Card | Online spending | Cashback on eligible online transactions |
| Amazon Pay ICICI Credit Card | Amazon shopping | Cashback on eligible Amazon purchases |
| HDFC Regalia Gold | Travel & lifestyle | Rewards and travel benefits |
| HDFC Infinia Metal | Premium spending | Premium rewards and travel benefits |
| HDFC Millennia | Online shopping | Cashback on selected merchants |
| Tata Neu Plus HDFC Bank Credit Card | Tata ecosystem | NeuCoins and Tata brand benefits |
| RuPay Credit Cards | UPI spending | Rewards on eligible UPI transactions |
Benefits, fees and eligibility can change, so always check the bank’s latest terms before applying.
1. SBI Cashback Credit Card
The SBI Cashback Credit Card is one of the cards that online shoppers often consider because of its cashback structure.
The card offers cashback on eligible online and offline transactions. SBI Card currently lists 5% cashback on eligible online spends and 1% on eligible offline spends, subject to applicable limits and exclusions.
The card has an annual fee, although the fee can be waived if you meet the required annual spending threshold.
Who should consider it?
This card may make sense if:
- You frequently shop online
- A large portion of your spending happens through online merchants
- You prefer cashback instead of complicated reward-point systems
- You can meet the spending requirement for the annual fee waiver
However, don’t assume every online payment will qualify for cashback. Categories such as rent, fuel, utilities, insurance and certain other transactions may have different rules.
2. Amazon Pay ICICI Credit Card
If Amazon is one of your most-used shopping platforms, the Amazon Pay ICICI Credit Card is worth considering.
One of its biggest advantages is that it currently comes with no joining or annual fee.
Amazon Prime members can earn higher cashback on eligible Amazon purchases, while non-Prime customers receive a lower cashback rate. The card also provides cashback on certain eligible purchases outside Amazon.
The cashback is credited as Amazon Pay balance.
Who should consider it?
This card can be useful for:
- Regular Amazon shoppers
- Amazon Prime members
- People looking for a lifetime-free credit card
- Users who prefer straightforward cashback
If you rarely shop on Amazon, however, the card may not provide enough value compared with a card designed around your actual spending habits.
3. HDFC Regalia Gold Credit Card
HDFC Regalia Gold is aimed more at customers looking for a combination of rewards, lifestyle benefits and travel-related perks.
The card offers reward points on eligible spending and provides benefits such as airport lounge access and milestone-based rewards, subject to the applicable terms.
It also has a higher annual fee than many entry-level credit cards, although HDFC Bank provides a fee-waiver condition based on annual spending.
Who should consider HDFC Regalia Gold?
It may be worth comparing if you:
- Travel regularly
- Spend significantly on your credit card
- Want lounge access
- Prefer reward points over basic cashback
- Can comfortably meet the spending requirement
The important thing is to calculate the actual value you will receive instead of choosing the card simply because it is a premium card.
4. HDFC Infinia Metal Credit Card
HDFC Infinia Metal sits in the premium credit card segment.
It is designed for customers with high spending requirements and offers premium reward and travel-related benefits.
The annual fee is considerably higher than mainstream credit cards, so this is not necessarily a card for everyone.
Who should consider it?
It may be relevant for customers who:
- Have high annual spending
- Travel frequently
- Can make meaningful use of premium travel benefits
- Want to maximise reward points
- Meet the bank’s eligibility requirements
For someone with relatively low annual spending, paying a high annual fee may not make financial sense.
5. HDFC Millennia Credit Card
HDFC Millennia is another popular option for people who spend heavily with selected online merchants.
The card provides cashback on eligible transactions with certain merchants and a lower cashback rate on other eligible spending.
Its merchant-focused cashback structure makes it particularly interesting for people who regularly use online shopping, food delivery and other digital services.
Who should consider it?
You may want to compare this card if you regularly spend on:
- Amazon
- Flipkart
- Myntra
- Swiggy
- Zomato
- Other participating merchants
The exact cashback rates, caps and eligible transactions should be checked before applying because these terms can change.
6. Tata Neu Plus HDFC Bank Credit Card
If you regularly use Tata brands and the Tata Neu ecosystem, the Tata Neu Plus HDFC Bank Credit Card may be worth considering.
The card allows eligible users to earn NeuCoins on qualifying transactions.
This can be particularly useful if you already spend money across Tata’s ecosystem rather than changing your spending habits simply to earn rewards.
Who should consider it?
It may suit people who regularly use services or brands within the Tata ecosystem and want to collect NeuCoins through eligible spending.
Before applying, check how NeuCoins can be earned and redeemed under the current terms.
7. Credit Cards for UPI Payments
UPI-linked RuPay credit cards have become an important category in India’s credit card market.
They allow eligible credit card transactions through supported UPI platforms, which can make them convenient for everyday payments.
However, there is an important point to remember:
Not every UPI transaction automatically earns rewards.
The eligibility can depend on the card, merchant category and transaction type.
Before choosing a UPI credit card, check:
- Cashback or reward rate
- Monthly reward limits
- Eligible merchant categories
- Excluded transactions
- Annual fee
- Redemption value
How to Choose the Best Credit Card for You
Instead of searching for one “best credit card in India”, start by looking at your own spending pattern.
If you shop mostly online
A cashback-focused card may be more useful.
If you shop mostly on Amazon
An Amazon-focused card could provide better value.
If you travel frequently
Look for travel rewards, airport lounge access and milestone benefits.
If you use Tata brands regularly
A Tata Neu card may be worth comparing.
If you use UPI frequently
Consider a RuPay credit card that supports eligible UPI transactions.
If you have high annual spending
Premium cards can make sense if the rewards and benefits justify the annual fee.
What Should Beginners Look for in a Credit Card?
If you are getting your first credit card, don’t immediately choose a premium card simply because it offers more benefits.
Start with a card that matches your regular expenses.
For beginners, these factors are more important:
Low or manageable annual fee: Don’t pay a high fee for benefits you won’t use.
Simple rewards: Cashback can be easier to understand than complicated reward-point systems.
Fee waiver: Check how much you need to spend to get the annual fee waived.
Cashback limits: A card advertising 5% cashback may still have monthly or statement-cycle limits.
Exclusions: Read the list of transactions that don’t earn rewards.
Repayment: Most importantly, choose a card that you can use responsibly and repay on time.
Credit Card Mistakes You Should Avoid
A credit card can be useful, but rewards should never become a reason to spend more money.
For example, spending ₹20,000 unnecessarily just to earn a few hundred rupees in cashback doesn’t create real savings.
Also avoid carrying an unpaid balance simply to earn rewards. Interest and other charges can quickly outweigh the value of your cashback or reward points.
The smarter approach is simple:
Use your credit card for expenses you were already planning to make, and pay the bill on time.
Frequently Asked Questions
Which is the best credit card in India in 2026?
There is no single best credit card for everyone. The right card depends on your spending pattern, preferred rewards, annual fee and the benefits you can actually use.
Which credit card is best for cashback?
Cashback-focused cards such as the SBI Cashback Card and other merchant-specific cashback cards can be compared depending on where you spend most of your money.
Which credit card is best for Amazon shopping?
The Amazon Pay ICICI Credit Card is specifically designed around Amazon and Amazon Pay benefits, making it an option worth considering for frequent Amazon shoppers.
Which credit card is best for beginners?
Beginners should generally compare cards with simple rewards, manageable fees and benefits that match their regular spending rather than automatically choosing a premium card.
Are credit cards good for UPI payments?
RuPay credit cards can be used for eligible UPI transactions through supported platforms. However, rewards and transaction eligibility vary by card.
Is a credit card worth having?
A credit card can be useful when you use it responsibly, take advantage of relevant rewards and pay your outstanding balance on time. It becomes expensive when you regularly carry unpaid balances and incur interest and fees.
Final Word
The best credit card in India is not necessarily the card with the highest cashback, the most reward points or the most expensive benefits.
It is the card that fits your actual spending habits.
Before applying, look at your last three months of expenses and ask yourself where most of your money goes online shopping, Amazon, travel, dining, UPI or everyday purchases.
Then compare the annual fee, rewards, cashback limits, exclusions and redemption options.
A few minutes of comparison can help you choose a card that provides real value instead of simply looking attractive on paper.
Disclaimer: Credit card fees, cashback rates, reward structures, eligibility requirements and exclusions can change. Always check the issuing bank’s latest terms and conditions before applying.
Nitish Kumar Sharma is the Founder, Chief Executive Officer (CEO), and Editor-in-Chief of Learn Onex. He leads the platform’s vision, editorial strategy, content standards, and long-term growth initiatives with a focus on financial education and investor awareness.